The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
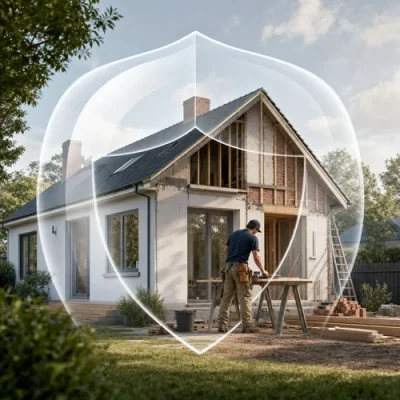
Renovating can improve your home's value, comfort and liveability, but it can also change the risks your insurer is covering. Before work starts, it is important to review your home and contents insurance, check exclusions and limits, and understand whether extra cover or policy changes may be needed during the project.
Why renovations can affect your home insurance
Many homeowners assume their standard home and contents insurance will automatically protect them throughout a renovation. That is not always the case. Renovation work can change the value of the property, introduce construction-related risks and alter the way the home is being used while work is underway.
A standard policy may provide cover for the building, contents and certain liability risks, but every policy has its own conditions, limits and exclusions. Depending on the nature and scale of the renovation, your insurer may need to know about the work before it starts. In some cases, you may need adjusted limits or additional insurance, such as renovation insurance or builder's risk-style cover, to address risks during construction.
The aim is not just to insure the finished renovation. It is also to understand what may or may not be covered while contractors, materials, temporary openings, structural changes or new fixtures are involved.
Review your current policy before work begins
Before starting any home renovation project, review your current insurance policy carefully. This helps you understand your potential financial responsibility if damage, theft or an accident occurs during the works.
Key areas to check include:
- whether renovations, alterations or building works are covered at all;
- whether there are limits on the size, value or duration of renovation works;
- whether damage caused by contractors working on your property is covered;
- whether accidental damage, liability or temporary structural exposure is excluded or limited;
- whether your contents remain covered if rooms are moved, stored or exposed during the project;
- whether you must notify the insurer before the renovation starts; and
- whether the finished work will increase the insured value of the home.
Policy exclusions can make a major difference to how a claim is assessed. If you are unsure where to start, it may help to review common home insurance exclusions and then compare those issues with the wording in your own policy.
For more context on exclusions, see common home and contents insurance exclusions in Australia.
Contact your insurer and ask specific renovation questions
After reviewing your policy, contact your insurance provider to clarify how your cover applies to the planned renovation. It is better to ask before work starts than to discover a limitation after an incident.
Useful questions may include:
- Do I need to notify you before the renovation begins?
- Does my current policy cover the type of work being carried out?
- Are there exclusions that apply while the home is under renovation?
- Are there limits based on the cost, duration or type of building work?
- Does my policy cover damage caused by contractors or subcontractors?
- Do I need to increase my building sum insured or contents limit?
- Is extra liability cover needed for the work being done?
- Will the policy need to be updated once the renovation is finished?
Keep notes of the discussion and any documents you receive. The important point is to have a clear understanding of your cover before materials are ordered, contractors are on site or structural work begins.
Check whether your insured value still matches the property
Renovations can increase the cost to rebuild or replace parts of your home. Adding rooms, upgrading kitchens and bathrooms, installing higher-value fixtures or adding outdoor structures can all affect how much insurance may be needed after the work is complete.
If the renovation increases the value or replacement cost of the property, your existing cover limits may no longer reflect the updated home. This can create a risk of underinsurance if the sum insured is not reviewed.
The same applies to contents. New appliances, furnishings, fittings or equipment may increase the value of what is inside the home. Review both the building and contents components of your policy when the project is complete.
For a broader explanation of insured values, see sum insured, rebuild costs and underinsurance in home insurance.
Consider the type and scale of renovation work
Not all renovations create the same insurance issues. A minor cosmetic update may have different implications from a structural extension, bathroom rebuild, roof alteration or swimming pool installation.
When planning the project, consider:
- Time frames: longer projects may expose the property to different risks for an extended period.
- Materials: building materials and fixtures stored on site may need to be considered.
- Costs: the project budget can affect whether existing limits remain appropriate.
- Permits and building requirements: some renovations may require approvals or must comply with local building rules.
- Temporary changes: openings, scaffolding, relocated contents or restricted access may affect risk.
- New liability exposures: additions such as a swimming pool may require a closer look at liability cover.
Planning the practical side of the renovation and the insurance side together can reduce surprises. It also gives you time to seek clarification before decisions are locked in.
Confirm contractor insurance arrangements
Renovation projects often involve builders, tradespeople and subcontractors. Your own home insurance may not automatically respond to every problem caused by someone working on the property, so it is important to understand both your cover and the contractor's insurance arrangements.
Before work begins, ask contractors what insurance they hold and whether it applies to the work being performed at your property. You may also want to clarify who is responsible for materials, tools, temporary works and damage caused during construction.
This does not replace checking your own policy. Instead, it helps you understand where responsibilities may sit if something goes wrong during the renovation.
When additional renovation cover may be worth discussing
Some renovation projects may require more than a simple update to a standard home and contents policy. Depending on the work, your insurer or insurance professional may discuss additional cover, higher limits or a different policy structure for the construction period.
Additional insurance may be relevant where the project is substantial, involves structural changes, significantly increases the home's value or introduces new risks that the standard policy does not address. The right approach depends on the policy wording, the renovation contract and the work being carried out.
The important step is to ask the question early. If your current policy does not cover the renovation risk, you may have time to consider alternatives before the work begins.
Working with an insurance broker
Some homeowners choose to speak with an insurance broker when planning a renovation, particularly where the project is complex or the policy terms are difficult to interpret. A broker may help identify relevant questions, compare available policy features and explain how different forms of cover may apply to the renovation period.
Because each renovation project is different, a standard approach may not answer every issue. A broker can help focus the discussion on the specific works, the property, the contractors involved and the possible gaps in existing cover.
You can learn more about the role of insurance brokers if you are considering professional assistance.
Insurance checklist before renovating
| Step |
What to check |
| Review your policy |
Look for renovation exclusions, limits, notification requirements and liability conditions. |
| Contact your insurer |
Ask how the planned work affects your current home and contents insurance. |
| Check contractor cover |
Confirm whether contractors have their own insurance for the work being performed. |
| Review insured values |
Consider whether the renovation changes the building sum insured or contents value. |
| Consider extra cover |
Ask whether renovation insurance, builder's risk-style cover or adjusted limits are relevant. |
| Reassess after completion |
Update your policy details once the renovation is finished and the home has changed. |
After the renovation is complete
Insurance planning should not stop when the builder leaves. Once the work is complete, review the policy again to make sure the renovated property is accurately described and insured for its updated value and features.
This is especially important if the renovation added new rooms, improved the quality of finishes, changed the layout, added a pool or increased the value of contents. Keeping the policy up to date can make future claims simpler to assess because the insurer has a clearer record of the property being covered.
Key takeaway
Home renovations can improve a property, but they can also change what your insurance needs to cover. Before starting work, review your policy, speak with your insurer, check contractor insurance and consider whether your building or contents limits need to change. A little preparation before the renovation begins can help you understand the risks and avoid relying on assumptions about cover.
Published: Friday, 28th Apr 2023
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.